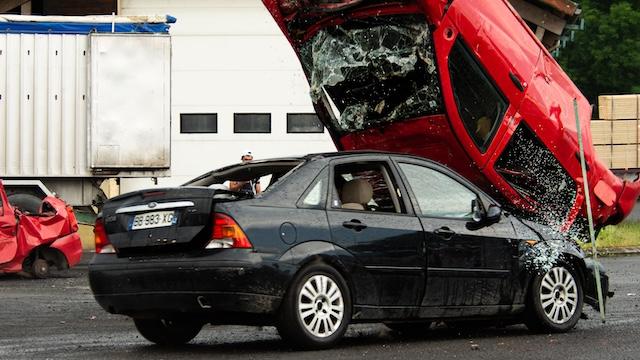
Imagine you’re driving home from work when another driver runs a red light and crashes into your vehicle. You’re shaken up, your car is damaged, and you may need medical attention.
The police arrive, determine the other driver was at fault, and then comes the news you weren’t expecting: The driver has no auto insurance.
Now what?
It’s a situation no driver wants to face, but it raises an important question: Who pays when the person responsible for an accident doesn’t have the insurance or financial resources to cover the damage?
That’s where uninsured motorist coverage can make a significant difference.
What is uninsured motorist coverage?
Uninsured motorist coverage, often called UM coverage, is designed to help protect you when you’re involved in an accident caused by a driver who doesn’t carry liability insurance.
Depending on your policy, this coverage may help pay for:
- Medical expenses resulting from injuries
- Lost wages if injuries prevent you from working
- Pain and suffering associated with covered injuries
- Damage to your vehicle, when uninsured motorist property damage coverage applies
Without this protection, you could find yourself relying on your own health insurance, collision coverage or personal savings to handle expenses caused by someone else’s mistake.
And while you may have the legal right to pursue the at-fault driver for damages, collecting money from someone who has few financial resources can be difficult.
What if the other driver has insurance, but not enough?
Having insurance doesn’t always mean having enough insurance.
Tennessee requires drivers to carry minimum liability insurance limits of $25,000 for bodily injury or death to one person, $50,000 for bodily injury or death to two or more people in one accident, and $25,000 for property damage in one accident.
Consider what happens when an accident causes $60,000 in medical expenses, but the at-fault driver’s policy provides only $25,000 in bodily injury liability coverage for one person.
That leaves a substantial gap.
Underinsured motorist coverage may help bridge that gap, subject to your policy limits, applicable offsets and other policy provisions.
With today’s medical costs and vehicle repair expenses, even a driver who meets Tennessee’s legal insurance requirements may not carry enough protection to cover a serious accident.
Isn’t uninsured motorist coverage automatically included?
In Tennessee, uninsured motorist coverage generally must be offered with automobile liability insurance, but drivers can reject it in writing or select lower limits as permitted by law.
That means you shouldn’t assume you’re protected simply because you have an auto insurance policy.
It’s worth checking your declarations page or asking your insurance agent whether you have uninsured and underinsured motorist protection, what limits apply and whether property damage coverage is included.
What about hit-and-run accidents?
Uninsured motorist coverage may also provide protection in certain hit-and-run situations.
However, coverage depends on the circumstances of the accident and the requirements of your policy and Tennessee law.
Reporting the incident promptly, documenting the damage and contacting your insurance company are important steps.
Three questions worth asking your insurance agent
Before your next policy renewal, take a few minutes to review your coverage.
- Do I have uninsured and underinsured motorist coverage? Don’t assume it’s included without checking.
- Are my coverage limits enough? Consider the financial impact of a serious accident involving medical bills, lost income or significant vehicle damage.
- Does my policy cover damage to my vehicle? Uninsured motorist bodily injury coverage and property damage protection serve different purposes. Ask about deductibles and limitations.
Protection before you need it
Most drivers purchase auto insurance hoping they’ll never have to use it. But insurance isn’t just about meeting state requirements. It’s about protecting yourself and your family when something unexpected happens.
You can be a careful driver, obey every traffic law and still find yourself facing thousands of dollars in expenses because someone else wasn’t properly insured.
The best time to discover a gap in your coverage is before an accident, not afterward.
Amy Harrington Bible is a feature writer for KnoxTNToday, writing a weekly column that will offer valuable insights and practical tips to enhance daily life. Amy Harrington Bible is the owner of Harrington Insurance Agency, a company that has been offering independent insurance services in the Knoxville, TN area since 1942. Bible carries the legacy of the family-owned and operated business with the skills and experience to meet any insurance need you may have.
Follow KnoxTNToday on Facebook, Instagram, X, LinkedIn and TikTok. Get all KnoxTNToday articles in one place with our free newsletter. Comments may be sent to news@knoxtntoday.com.