Preparing for the unexpected doesn’t mean giving up independence. It means making sure someone you trust knows where to turn when help is needed.
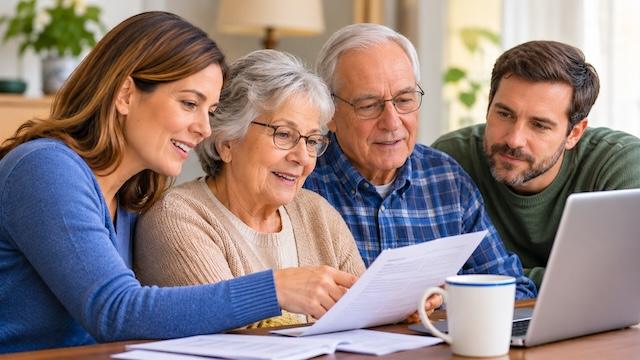
There comes a time in many families when the roles begin to shift. Parents who once managed every household decision may find themselves needing a little assistance, while adult children begin asking questions they never imagined asking.
One of those questions can be particularly uncomfortable: Should adult children know where their parents keep their financial information?
The answer is generally yes, but with an important distinction. Knowing where financial information is located is different from having access to someone’s money or control over financial decisions.
For many families, simply having a plan can make an enormous difference during an unexpected illness, hospitalization or death.
A conversation worth having before a crisis
Imagine a parent who is suddenly hospitalized and unable to communicate. Bills continue arriving, insurance premiums are due, and important financial documents are needed. The adult children want to help, but no one knows which bank their parent uses, where the insurance policies are kept or whether a power of attorney exists.
What might have been a manageable situation quickly becomes stressful.
These circumstances are not limited to older adults. Accidents and unexpected medical emergencies can happen at any age.
The best time to organize financial information is when everyone is healthy, comfortable and able to participate in decisions.
What information should families know?
Parents do not necessarily need to share account balances, passwords or personal spending details. However, a trusted family member should know how to locate essential records when necessary.
A practical family financial information plan might include:
- Banking information: Names of banks or credit unions where checking, savings and certificates of deposit are held.
- Retirement and investments: Contact information for financial advisors and institutions managing retirement accounts.
- Insurance policies: Locations of life, health, long-term care, homeowners and other important insurance documents.
- Legal documents: Where wills, trusts, powers of attorney and advance healthcare directives are stored.
- Household obligations: Information about mortgages, utilities, recurring payments and other financial commitments.
- Professional contacts: Names and telephone numbers of attorneys, accountants, insurance agents and financial advisors.
- Digital accounts: Instructions for accessing a secure password manager or other protected digital records when legally authorized.
The goal is not to create a detailed financial report for the entire family. It is to establish a reliable path to important information if circumstances require it.
Independence and privacy still matter
Some parents hesitate to discuss financial matters because they fear losing control or becoming dependent on their children.
Those concerns deserve respect.
A parent who is capable of managing personal finances should remain in charge of those decisions. Sharing the location of important documents does not automatically authorize someone else to make withdrawals, change accounts or direct investments.
Families should also understand that being listed as an emergency contact or knowing an account number does not provide legal authority to conduct transactions.
A properly prepared durable financial power of attorney can designate someone to act on another person’s behalf under specified circumstances. The document’s provisions and applicable state law determine when that authority begins and what actions are permitted.
An attorney can help families determine which arrangements are appropriate.
Choosing the right person
Not every adult child needs access to every financial detail.
Parents may prefer to designate one trusted individual as the primary contact and another as a backup. That person might be an adult child, spouse, sibling or another responsible individual.
The most important considerations are trust, reliability, good judgment and a willingness to respect the parent’s wishes.
It is also wise to communicate the existence of a plan to appropriate family members, even when only one person has been designated to manage financial matters. Clear communication can reduce misunderstandings later.
Protecting financial information from fraud
Organization should never come at the expense of security.
Families should avoid keeping unprotected lists of passwords, Social Security numbers and account information in easily accessible places. Sensitive information should be stored securely, and access should be limited to those who genuinely need it.
Older adults can be particularly vulnerable to financial exploitation, including scams involving individuals who pretend to represent banks, government agencies or even family members.
A trusted contact at a financial institution may help the institution reach someone when concerns arise, but that designation does not ordinarily grant the contact access to account funds.
Parents and adult children can ask their financial institution about available safeguards and trusted-contact procedures.
Start with a simple question
Financial conversations do not have to begin with requests for account information.
An adult child might simply ask, “If something happened and you needed help, would I know where to find your important papers?”
That question opens the door without challenging a parent’s independence.
Parents can also initiate the conversation by telling their children that they have organized important information and want someone to know where it is kept.
The discussion can happen gradually. One afternoon might be devoted to locating insurance policies, another to reviewing legal documents and another to identifying financial contacts.
What matters is beginning.
A gift of preparation
Families often spend considerable time planning vacations, celebrations and major purchases. Yet many postpone the conversations that could make the greatest difference during a difficult time.
Knowing where important financial information is kept is not about anticipating the worst. It is about reducing confusion, protecting independence and helping loved ones respond with confidence when circumstances change.
The greatest gift may not be access to a parent’s finances, but the peace of mind that comes from knowing a thoughtful plan is already in place.
First Horizon encourages families to consider the importance of financial organization and planning for life’s changing circumstances. A conversation with a trusted banking professional, financial advisor or attorney can help identify appropriate next steps.
Learn more about financial services and resources at First Horizon.
This article provides general educational information and is not intended as individualized legal or financial advice.
First Horizon Bank is a leading regional financial services company, dedicated to helping our clients, communities, and associates unlock their full potential with capital and counsel. It’s the powerful tools you need with the personal service you deserve. Contact First Horizon for all your banking needs.
Take a puzzle break! Play WordRow, Sudoku or Crosswords today! Choose your favorite puzzle in the site navigation.
Follow KnoxTNToday on Facebook, Instagram, X, LinkedIn, and TikTok. Get all KnoxTNToday articles in one place with our free newsletter. Comments may be sent to news@knoxtntoday.com.