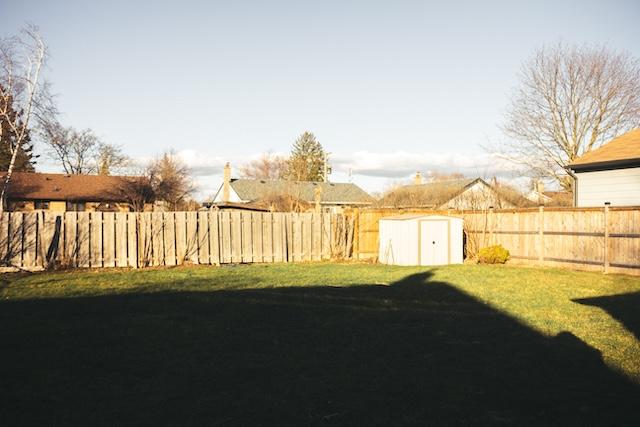
You probably know your homeowners insurance protects your house. But what about the storage shed in your backyard, the fence surrounding your property or the detached garage where you park your car?
The good news is that most standard homeowners insurance policies provide some protection for these structures. The important question is whether you have enough coverage.
What is other structures coverage?
Most homeowners policies include something called Coverage B, commonly known as other structures coverage. It generally protects structures on your property that are separate from your home.
Examples include detached garages, storage sheds, fences, gazebos and certain other outdoor structures.
If a covered windstorm damages your shed or a fire destroys your detached garage, this portion of your policy may help pay for repairs or replacement.
How much coverage do you have?
Here’s something that surprises many homeowners: Other structures coverage is typically limited to 10% of the amount of insurance on your house.
For example, if your home is insured for $300,000, your policy may provide $30,000 in coverage for all your detached structures combined.
That might sound like plenty until you consider the cost of replacing a detached garage, a large storage building and several hundred feet of fencing.
If you’ve added outdoor improvements since purchasing your home, your existing coverage might not be enough.
What about the things inside your shed?
There’s an important distinction between the building itself and what’s stored inside.
Your shed may be covered under other structures coverage, while your lawn mower, tools, bicycles and other belongings generally fall under the personal property portion of your homeowners policy.
Those belongings may have different limits or exclusions, so it’s worth reviewing both types of protection.
What isn’t covered?
Homeowners insurance isn’t designed to pay for every type of damage.
Common exclusions include flooding, earthquakes, normal wear and tear, deterioration and damage caused by poor maintenance.
For example, a fence damaged by a covered windstorm may qualify for protection. A fence that collapses because its wooden posts have rotted generally will not.
There can also be restrictions on detached buildings used for business purposes or rented to someone else.
And remember, your deductible generally applies when you file a covered claim.
Three questions worth asking your insurance agent
Before the next storm arrives, take a few minutes to review your property and ask:
- Do I have enough coverage to replace all my detached structures?
- Would my policy pay replacement cost or depreciated value for my fence, shed or garage?
- Do any of my outdoor structures require additional coverage because of their value or how they’re used?
If you’ve recently built a workshop, installed an expensive fence or added a detached garage, don’t assume your insurance automatically provides enough protection.
Amy’s advice: Your homeowners insurance should reflect everything you’ve invested in your property, not just the house itself. A quick coverage review today could prevent an expensive surprise tomorrow.
Amy Harrington Bible is a feature writer for KnoxTNToday, writing a weekly column that will offer valuable insights and practical tips to enhance daily life. Amy Harrington Bible is the owner of Harrington Insurance Agency, a company that has been offering independent insurance services in the Knoxville, TN area since 1942. Bible carries the legacy of the family-owned and operated business with the skills and experience to meet any insurance need you may have.
Follow KnoxTNToday on Facebook, Instagram, X, LinkedIn and TikTok. Get all KnoxTNToday articles in one place with our free newsletter. Comments may be sent to news@knoxtntoday.com.