Most homeowners know what they paid for their house. They probably have a good idea what it could sell for today.
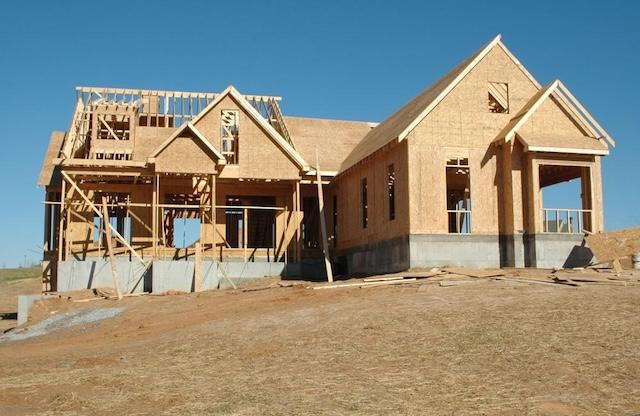
But there is another number that may matter even more after a disaster: What would it cost to rebuild the house from the ground up today?
Those numbers are not necessarily the same.
A homeowners insurance policy generally bases dwelling coverage on the estimated cost to reconstruct the home, not its market value. That distinction can become painfully important following a fire, tornado or other covered loss that destroys a house.
Rebuilding costs can change
Construction costs do not stand still. Lumber, roofing, concrete, appliances and other materials can rise in price, as can wages for electricians, plumbers, roofers and other skilled workers.
Following a widespread disaster, costs also can increase because many homeowners are competing for the same contractors and materials.
A house that was adequately insured several years ago, therefore, may not necessarily carry enough dwelling coverage to rebuild today.
Homeowners should review the Coverage A — Dwelling amount on their insurance declarations page. That figure is generally the starting point for determining how much insurance is available to repair or rebuild the structure after a covered loss.
But don’t stop with the number.
Replacement cost isn’t market value
A home’s real estate value includes factors such as the land, location, school district and demand in the neighborhood. Rebuilding cost is based on what it would take to reconstruct the physical house.
That can include materials and labor as well as demolition, debris removal and costs associated with meeting current building codes.
In some cases, rebuilding an older home can be particularly expensive because materials, craftsmanship or architectural details are difficult to duplicate.
Homeowners who have remodeled also should take another look at their policies. A new kitchen, finished basement, room addition, upgraded flooring or other substantial improvement can increase replacement costs.
Ask about the protection behind the number
Insurance policies aren’t all structured the same way.
Ask your agent whether your policy includes extended replacement cost coverage, which may provide additional coverage above the stated dwelling limit when rebuilding costs exceed expectations.
Some insurers also offer guaranteed replacement cost coverage, which can provide broader protection for rebuilding a home after a covered loss, subject to the policy’s terms and exclusions.
Another consideration is ordinance or law coverage. If an older home must be rebuilt to comply with today’s electrical, plumbing, energy or other building codes, those required upgrades can add significantly to the bill.
And remember that rebuilding the house is only part of recovering from a major loss. Review coverage for personal belongings and additional living expenses, which can help with eligible costs of living elsewhere while the home is being repaired or rebuilt.
Five questions worth asking
A quick conversation with your insurance agent can begin with these questions:
- What is my home’s estimated replacement cost today?
- When was that estimate last updated?
- Does my policy include extended or guaranteed replacement cost coverage?
- Do I have adequate ordinance or law coverage?
- Have renovations or additions changed the amount of insurance I need?
The goal isn’t simply to carry more insurance. It is to carry the right amount of insurance for the house you own today.
Pull out your declarations page before the next renewal and look at that dwelling coverage number. If you don’t know how it was calculated — or whether it would realistically rebuild your home — ask.
The worst time to discover a coverage gap is when the house that number is supposed to protect is gone.
Amy Harrington Bible is a feature writer for KnoxTNToday, writing a weekly column that will offer valuable insights and practical tips to enhance daily life. Amy Harrington Bible is the owner of Harrington Insurance Agency, a company that has been offering independent insurance services in the Knoxville, TN area since 1942. Bible carries the legacy of the family-owned and operated business with the skills and experience to meet any insurance need you may have.
Follow KnoxTNToday on Facebook, Instagram, X, LinkedIn and TikTok. Get all KnoxTNToday articles in one place with our free newsletter. Comments may be sent to news@knoxtntoday.com.